How to Buy a Home with lCLT: Affordable Homeownership for Lahaina ‘Ohana
1. Household Income
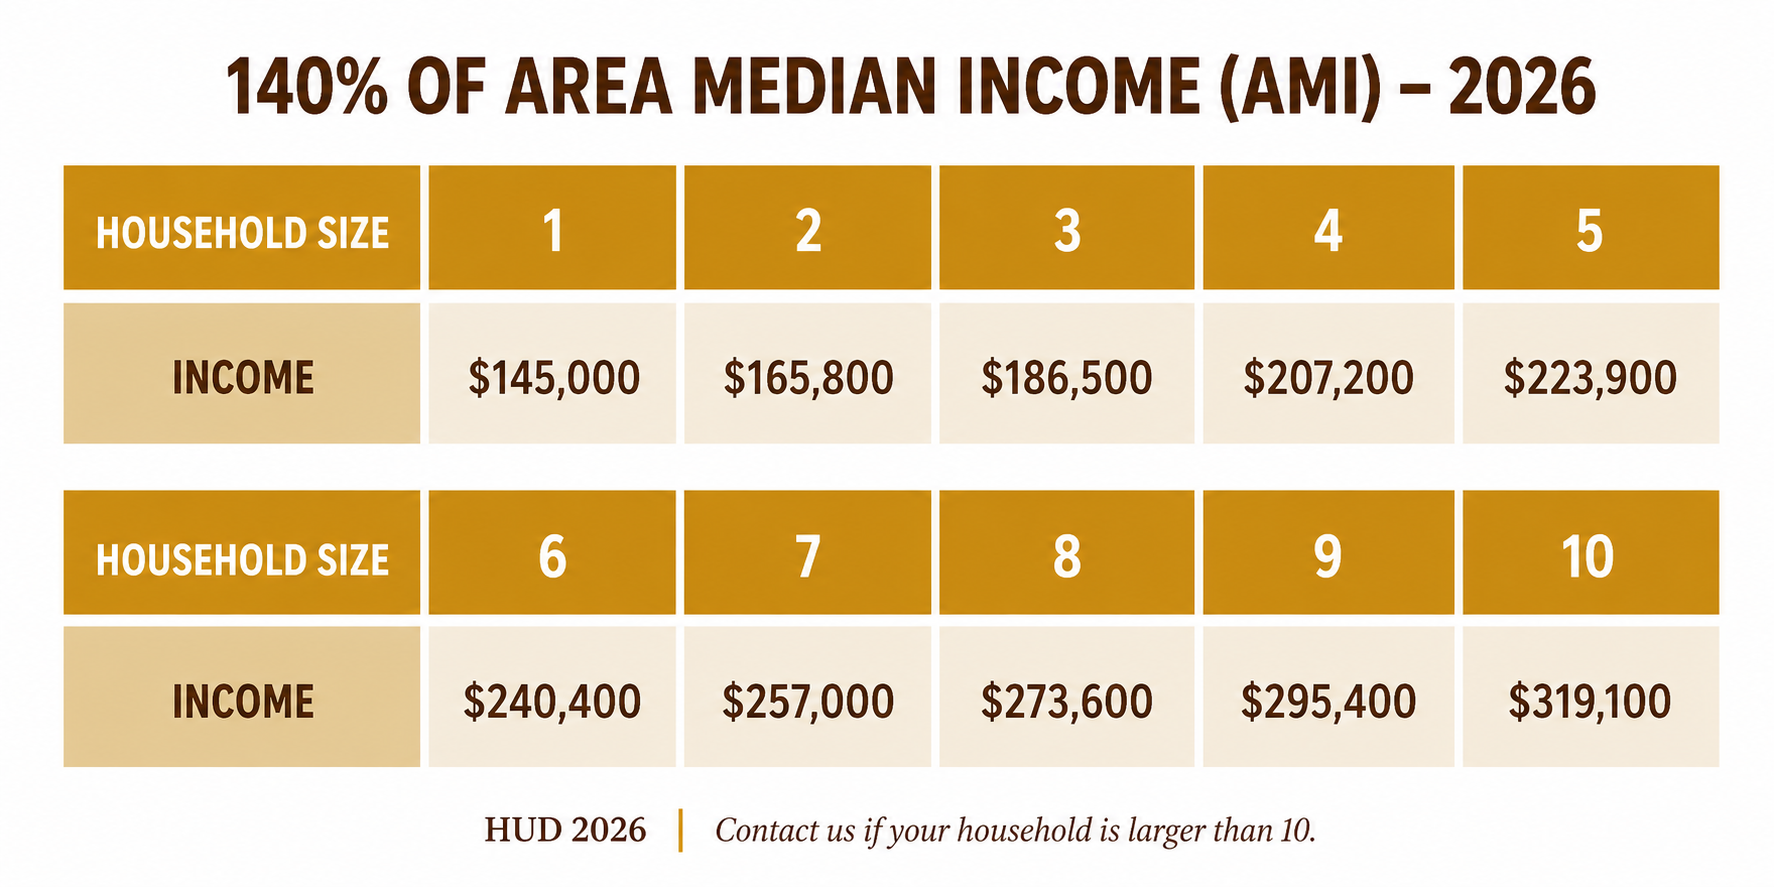
To be eligible to purchase a Lahaina Community Land Trust home your gross household income may not exceed $300,000 or 140% of Area Median Income (see chart below), whichever amount is greater.
Each LCLT home uses different funding sources to make it affordable, therefore there are different income requirements depending on which home you purchase. Income limits include:
2. Connection to Lahaina
At this time, homeownership opportunities are prioritized for households whose homes were damaged or destroyed in the 2023 Lahaina fires and who currently reside on Maui. As the program grows, additional opportunities may become available for other households. We encourage all interested households to complete the Homebuyer Intake Form to stay connected for future opportunities.
3. Household Savings & Assets
Your household must have a minimum of $1,000 in liquid assets to qualify to purchase a LCLT home. Household assets include all checking, savings and investment accounts and do not include IRS designated retirement accounts. Your total non-retirement assets may not exceed $500,000.
Additionally, please note that you cannot buy LCLT home if you have more than a 33% interest in another residential property.
4. Financing Your home
Most buyers will work with a lender to finance their home. While LCLT is not a lender, we partner with trusted organizations who can help guide you through that process. Lenders typically look at a few key things when determining loan eligibility:
Income: You must be able to document adequate, steady household income so that your house payment does not exceed 30% of your gross monthly income.
Credit & Financial History: A credit score of 620 or higher is generally needed to qualify for a mortgage, depending on your lender. If your score is lower, you may still be eligible based on compensating factors. If you do not have a credit score, eligibility may be determined based on documented alternative credit history (such as utility bills, landlord references, etc).
Maximum Debt: Your total debt payments, including your future house payment, should generally be at or below 44% of your gross monthly income, depending on your lender.
If you’re not sure where you fall, that’s completely okay. We’re here to help you understand your options and connect you with the right resources.
Steps to LCLT Homeownership
The steps in LCLT’s home-buying process are designed to ensure we have all the information needed to help you successfully obtain a mortgage and purchase your LCLT home.
The information you share will be kept confidential and used only to support your household and help us determine your eligibility for housing opportunities.
Our process is also designed to ensure you have all the information you need to feel confident if/when you decide to buy a home and understand what is involved. If you have questions, please email us at ComeHome@LahainaCommunityLandTrust.org
Steps to becoming an LCLT homeowner:
Get started: Be ready with your ‘ohana’s information, including household size, household income and non-retirement assets, and the total years lived in the Lahaina area (96761) for the applicant or co-applicant who has lived there the longest. Please ensure all information is accurate and can be verified.
Submit a short intake form: (one per household, please) We use this information to learn about your household and determine your eligibility for future housing opportunities and lotteries. After completing the intake form, check your email and click the verification link to complete your submission.
Join the lottery when homes are available: If a home matches your household’s needs, we’ll invite you by email (and text, if you opted in) to complete a lottery screening form using your unique link. Households who submit the form will be entered into a fair and random lottery conducted by an independent third party.
If selected in the lottery, complete an application: The top 10 households selected through the lottery are prioritized based on years lived in the Lahaina area (96761 zip code) by the applicant or co-applicant who has lived there the longest. If households have the same number of years in Lahaina, priority will follow the original lottery order.
If invited to apply, you will be asked to verify this person’s residency and submit supporting documentation, including financial information. Any misrepresentation or failure to verify information will result in ineligibility.
Being invited to apply does not guarantee a home. Homes are offered to qualified applicants in priority order, and additional applicants may be considered if earlier applicants are not eligible or choose not to move forward.
Secure financing: Complete a homebuyer education course with an LCLT partner, such as Fannie Mae, and work with a lender to understand your options and secure financing for your home.
Purchase your LCLT home!
fAQs About LCLT’s Path To Homeownership
-
Please read this How to Qualify page for eligibility information!
-
First, let’s explain how a community land trust works. This 90 second video explains the basic community land trust model, which Lahaina CLT is using.
We come to this work with the understanding that the uncontrolled, over commodification of ʻāina is the root cause of our communityʻs displacement, and once we secure a parcel, we are effectively buying that ʻāina out of the market, and into community hands, forever. That means, once we purchase a vacant lot, we donʻt sell it.
We build homes on top of that land, and sell the homes to folks, but the ʻāina stays in trust, forever. Homebuyers get all the benefits of homeownership: limited equity, stability, agency over their life and home, and their homeownership is tied to the ʻāina with a 99 year ground lease that is inheritable, transferrable and renewable.
LCLT homeowners are owners of the home, and stewards of the ʻāina. -
Homeownership opportunities will be available at different price points based on household income. Homes are priced so that monthly housing costs generally do not exceed 30% of a household’s income. The minimum annual household income required is $30,000.
-
We recommend the course offered by the Federal National Mortgage Association (FNMA), commonly known as Fannie Mae. Another option is Hale Mahaolu Homeownership Counseling Program.
Households who have submitted LCLT Homebuyer Intake Form may also receive updates about personalized support programs as they arise through our partner agencies.
-
Being preapproved is not required to enter a lottery. However, it is helpful to go through the pre-approval process, as it gives you a solid reference for your buying power. We will give you the opportunity to get pre-approved if you are selected in the housing lottery.
-
Read about some lender resources here.
-
Lotteries will be held throughout the year as homes or homebuilding opportunities become available, for many years to come. A lottery may include one home or multiple homes.
Based on your intake form responses, if you appear to qualify for an available home, you will receive an invitation by email and, if you opted in, by text message. The first several home lotteries will be for fire-impacted families.
-
Of course not! Opting out of one lottery will not affect your eligibility to receive invitations to future lotteries.
-
Please complete a new Homebuyer Intake Form using the same email address you used on your original form, if possible.
-
There is no deadline. However, to be considered for a specific lottery, you must complete the Homebuyer Intake Form before that lottery opens.
-
First, submit one LCLT Homebuyer Intake Form per household. When a home becomes available, households that appear to qualify based on their intake form responses will receive an email invitation with a unique lottery link. If you opted in to text messages, you will also receive a text letting you know that the invitation was emailed.
Use the link to complete and submit the lottery form. You will then receive an automated email confirming whether you are eligible for that lottery. If you make a mistake, click the link again and resubmit the form.
The lottery typically closes within two weeks and is conducted using an independent, neutral third-party lottery administrator called Public House. You will receive an email notifying you whether your household was drawn into the top 10. -
To protect the privacy of all homebuyers, lottery participants cannot attend. The lottery is conducted electronically in the presence of LCLT staff and, in some cases, partner agencies. With a single click, the results, including the names of all entries, are immediately displayed on the screen.
The process and audit log are automated through Public House, an independent, neutral third party specializing in lottery and application management. All lottery participants will be notified of the results on the same day the lottery is held.
-
Households drawn into the top 10 will be invited to complete a full application for the home. Once the length of time each applicant and co-applicant has lived in the Lahaina area (96761 zip code) has been verified, priority will be given to the household with the longest tenure in 96761.
If you are not selected for the home, your application will remain in our system. You can continue to access and update it as needed for future homeownership opportunities.
-
Report pension payments as income only if you are currently receiving them. If you are not receiving payments and cannot access or liquidate the pension funds, they are generally not considered current income or an available asset.
-
No, you do not include household members under age 18 income on your application.
-
No, a vehicle is not considered an asset for the purpose of home buying.
-
The timeline depends on your circumstances and the homes available. Completing the Homebuyer Intake Form is the first step. Depending on your situation, it could be weeks, months, or longer before you are matched with an opportunity and invited to participate in a homebuyer lottery.
Most lotteries will be held one to two weeks after invitations are sent. Once a lottery is held, the top 10 households will be invited to complete the full homebuyer application, which typically takes approximately two weeks.
If you are at the top of the list, meet all eligibility requirements, and have the funds or financing needed to purchase the home, the closing timeline will depend on your lender and whether the home has already been built. Closing on a completed home typically takes 30 to 60 days. If the home has not yet been built, construction typically takes approximately nine months, after which you will close and move in.